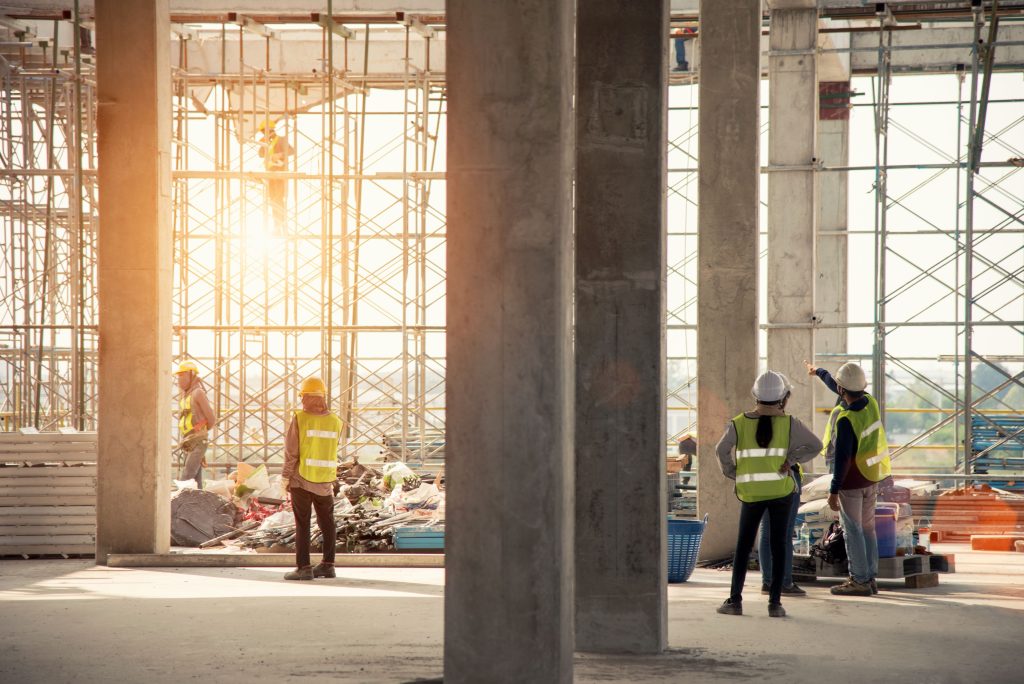
Every construction project relies on people, equipment and careful coordination. When machinery is damaged, materials are stolen or an incident occurs on site, the impact can extend beyond the immediate repair bill.
Construction insurance helps protect your business against a range of risks, from damage to works in progress through to liability claims. The right combination of policies depends on the work you do, the equipment you use and the responsibilities you take on.
At MKP Insurance, we take the time to understand your operations and arrange cover that reflects how your business actually works.
Understanding the Risks in Building and Construction
Builders, civil contractors, earthmoving businesses and subcontractors face different exposures. Your risks can also change between projects.
Common concerns include:
- Accidental damage to works under construction.
- Theft of tools, machinery and building materials.
- Damage to underground services or neighbouring property.
- Injury to third parties.
- Storm, fire and other weather-related damage.
- Claims arising from professional advice or design.
- Cyber incidents affecting business systems and information.
A policy arranged for one type of work may need updating when you take on larger projects, expand your services or start working in new locations.
What Types of Construction Insurance Should You Consider?
Contract Works Insurance
Contract works insurance can cover insured physical loss or damage to a project during construction, including works in progress and construction materials.
Depending on the policy, cover may include events such as fire, storm, theft and accidental damage.
Check how the policy treats flood, existing structures, materials stored off site and defects. Public liability may be included in a combined policy or arranged separately.
Plant and Equipment Insurance
Excavators, loaders, cranes and other machinery are central to keeping projects moving.
Plant and equipment insurance can help cover insured loss or damage to your machinery. Your cover should reflect whether equipment is owned, financed or hired, and how it is used, stored and transported.
Mechanical breakdown, hired-in plant and hire costs following damage may require specific cover or extensions.
Public and Products Liability Insurance
Public liability insurance can help protect your business against claims for third-party injury or property damage arising from your operations.
For example, excavation work could damage a neighbouring property or underground services. Whether a claim is covered depends on the circumstances and policy terms.
Your declared activities, subcontractor arrangements and contractual responsibilities all need careful consideration.
Commercial Motor and Fleet Insurance
Work vehicles often carry more than people. They transport tools, materials and equipment between sites.
Commercial motor insurance can cover insured damage to your vehicles and liability for damage caused to other people’s property. A fleet policy may suit businesses operating multiple vehicles.
Check trailers, vehicle accessories and tools carried in vehicles separately, as these may need additional cover.
Professional Indemnity Insurance
Businesses providing design, specifications, technical advice or other professional services may face claims if an alleged error causes a client financial loss.
Professional indemnity insurance can help cover claims arising from those services, including associated legal defence costs.
This is particularly relevant when your responsibilities extend beyond carrying out construction work into design or advice.
Business Pack Insurance
Your office, workshop or storage premises also need attention.
A business pack can combine selected covers such as property damage, theft, glass, money and machinery breakdown. Business interruption cover may also be available to help with lost income and certain ongoing expenses following an insured event.
It is worth checking how these policies work alongside your site and equipment cover.
Cyber Insurance
Construction businesses rely on email, digital plans, project management systems and online payments.
Cyber insurance can help with incident response, data recovery, legal costs and business interruption following a covered cyber event.
Cover for fraudulent payments or social engineering varies, so check these exposures specifically rather than assuming they are included.
Workers Compensation
Workers compensation is a separate consideration for businesses employing staff. Requirements depend on the state or territory, and some contractor arrangements may also create obligations.
Check your responsibilities wherever your team works.
When Should You Review Your Construction Insurance?
Review your cover before starting a new project or making a significant change to your operations.
Useful questions include:
- Does the policy cover every activity we carry out?
- Are project values and equipment sums insured current?
- Does cover meet the insurance requirements in our contracts?
- How are hired equipment and subcontractors treated?
- What happens if a project is delayed or work stops?
- Which exclusions, excesses and conditions could affect a claim?
A certificate of currency confirms that a policy exists. Understanding the underlying cover is just as important.
Clear Advice. Ongoing Support.
At MKP Insurance, we understand the demands of construction and heavy industry. We work with you to identify your exposures, explain your options and arrange cover suited to your business.
Our service continues after your policies are in place. As your operations change, we help review your cover. If you need to make a claim, we guide you through the process and advocate on your behalf.
Talk to MKP Insurance for a no cost, no obligation discussion about protecting your construction business.
The information provided is general advice only and does not take into account your objectives, financial situation or needs. Consider whether it is appropriate for your circumstances and read the relevant policy wording and Product Disclosure Statement, where applicable. Cover is subject to policy terms, conditions, limits and exclusions.
Moody Kiddell & Partners (Insurance) Pty Ltd ABN 48 071 572 828, AFSL 512898.